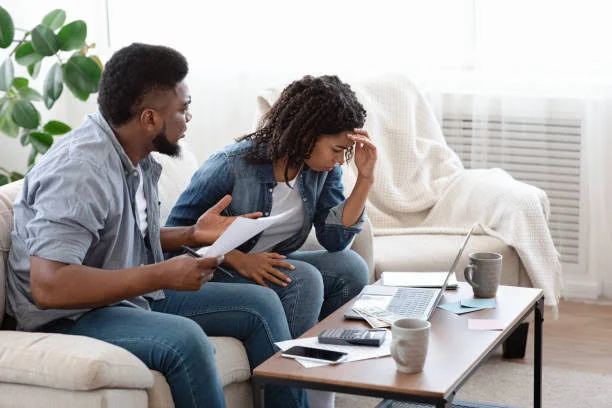
Unsurprisingly, as many as the number of relationships that experience money issues are, it is thankfully, an issue that can be avoided, or, to be more realistic, better managed.
Yes, it can be an uncomfortable conversation to have, granted, but it is one that has to happen.
Here’s how to handle money issues with your partner to reduce occurrences of arguments.
Have The Money Talk
Initiate and have the money conversation with your partner.
Broach the subject casually, and probably start by talking about your desire to open a family account to start saving towards buying a house, a car, etc.
Say something like “a colleague told me there are good housing deals in Ibeju-Lekki, maybe we could look it up together?”
Set an atmosphere where it would be easy to talk freely about your values around money, without fear of judgment.
Try to refrain from pointing the finger.
Dishing blame and arguing back and forth will not make any issues better.
Talk to him/her about your money-related feelings because often, people inherit the beliefs, values, and attitudes around money from their family.
So, before getting into the next argument about money, sit down and discuss how your partner relates to money.
Understanding their attitudes and views might explain why he is hesitant to have the discussion or why they feel the urge to overspend.
Whatever your partner’s money behaviour, it is important for you to understand it clearly.
Ask: “What did your family teach you about money?
Can you recall your first memory involving money?
What are your financial goals?
Was your family fearful about money when you were a kid? Do you have any fears around money?”
These questions will help you better get into their heads and understand their perception of money.
2. Decide On The Account Type(s) For Your Family
Put everything on the table.
Weigh the pros and cons, and decide if you will run a joint account or maintain separate ones. This is one of the money issues that people in a relationship often have.
Please keep in mind that having separate accounts doesn’t translate to spending recklessly, nor does merging all your funds in a joint account mean you can no longer spend as you ordinarily would have done.
You just have to work the fine details out for your unique relationship.
In any case, both partners should have access to the records of the other since you are sharing a household.
When you do, you can then determine who will be the primary overseer of your money, aka ‘the money handler’.
Usually, the person who is most organised/financially savvy is the best choice for managing the finances.
Even better, both partners should take on the responsibility in some way.
So, seek to allocate duties according to your individual strengths.
For example, you may be better at saving, so it makes sense that you’re in charge of building an emergency fund and overseeing retirement savings.
The other may be in charge of paying monthly bills and balancing the accounts.
3. Agree On Which Of You Will Handle Certain Expenses
You will need to be clear on who is writing the cheque for rent, paying the electric bill, attending to the kids’ school fees, and other household bills.
You do not want to get into a situation where both of you thought the other paid the NEPA bill and you learn that it wasn’t paid when the units run out, nor do you want to pay bills twice and short money on something else.
Also, being upfront about how much both of you make and how you will divide the bills will make things much easier.
Some families divide everything in half, while others just pool their money regardless of who makes what.
Regardless, a big-ticket item should be bought together or first talked about.
Establish boundaries about how much either of you can spend without talking to your spouse.
This can be as simple as saying you have a spending limit of N10,000 0r N50,000, as the case may be, without checking in since that is a low amount in your budget and won’t overdraw the account.
It all needs to be talked about.
4. Know Your Debt Situation And Decide On A Strategy To Pay It Off
Both of you should have a very clear idea of each other ‘s debt situation.
Don’t fall prey to the idea that it’s your partner’s problem—it’s not.
You’re now an item, so working together to shrink each person’s debt is ideal.
It can also be helpful to get financial advice or attend a debt reduction seminar for couples.
If you have a significant amount of debt or have no idea where to start to pay it down, it may be best to involve a professional who can assist you.
5. Plan For The Future
A good place to start is building an emergency fund.
If you both didn’t already have an emergency fund/savings wallet before getting married, now is the time to build one.
If nothing else, it will act as a cushion in times when unexpected expenses pop up or one of you is temporarily out of work.
How big your savings account is will depend on you and your partner.
Many families tuck away enough money for at least 6 to 12 months of expenses. This will provide greater security over the long haul.
This savings account would be for real emergencies only, not impulse buys. So, take the time to set boundaries as to what qualifies as an emergency.
In fact, it is not too early to start planning towards retirement.
Talk to your significant other and come up with a plan that suits both of you for retirement, and start saving towards it.
Bear in mind that they may have varying opinions when it comes to retirement, so be willing to compromise and consider your spouse’s perspective.
These tips would help you and your partner overcome money issues that may come up in your relationship.
Istanbul local experience tour The tour gave us unforgettable memories. https://cgslimited.com/?p=8116
9g2ei3
so7gmo
v9a9yd
https://t.me/officials_pokerdom/3554
https://t.me/s/Martin_casino_officials